Points vs. cash back: 3 numbers that decide which card earns more
Cash back is worth its face value; points are worth what you redeem them for. Compare earn rate, point value, and annual fee to see which pays you more.
Rewards cards pay you in one of two ways: cash back, or points and miles. Cash back is worth its face value. Points are worth whatever you redeem them for, and that can be less than, equal to, or more than a cent each. Three numbers settle which one earns you more.
Number 1: the earn rate
The earn rate is how much you earn per dollar spent. Cash back cards state it as a percentage; points cards state it as a multiplier. A card that earns 2% cash back and a card that earns 2X points look alike, but they are not comparable until you know number 2.
Most cards have a base rate on all purchases and bonus categories that earn more, such as dining or groceries. Your mix of spending decides which rate most of your money earns.
Number 2: what a point is worth
For cash back, this number is always one: one cent per cent earned. For points, it is the value you get per point at redemption, in cents:
- About 1 cent on many programs, for travel booked through the issuer or a statement credit.
- Less than 1 cent for some redemptions: some programs pay less for cash, merchandise, or gift cards.
- More than 1 cent when you transfer points to an airline or hotel partner and book an award that would cost a lot in cash.
So the real return on a points card is earn rate × value per point. A card earning 3X on dining returns 3% if points are worth one cent, and more only if you redeem them for more.
Number 3: the annual fee
Points cards that offer transfer partners often charge an annual fee; many flat-rate cash back cards do not. The fee comes off the top. A points card has to out-earn a no-fee cash back card by at least its fee each year to be the better deal.
The flat-rate cash back baseline
Flat-rate cash back cards earn the same rate on every purchase with no categories to track. They are the baseline any points card has to beat.
| Feature | 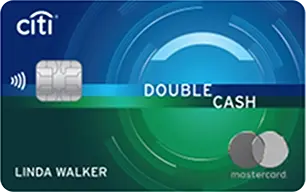 |  |  |
|---|---|---|---|
| Annual fee | $0 | $0 | $0 |
| Welcome offer | $200 cash back | $100 cash back | $200 cash back |
| Base rate | 2% | 2% | 1.5% |
| Bonus categories |
| — |
|
| Travel insurance | |||
| Rental car insurance | |||
| Cell phone protection | |||
| Purchase protection |
Citi Double Cash Card earns a base rate of 2% with an annual fee of $0. There is nothing to value and nothing to learn: the return is the rate.
When points win
A points card with transfer partners pulls ahead when all three of these are true:
- Most of your spending falls in its bonus categories.
- You redeem through partners for well above one cent per point.
- The extra return beats the annual fee by a margin you care about.
Who should pick cash back
- You want a return you can see on your statement without planning a redemption.
- You do not travel enough to use airline or hotel transfers.
- You would rather not pay an annual fee.
For most people starting out, a no-fee flat-rate card is the right first card. A points card makes sense once you know you will use its partners, and our card pages show each card's categories and program so you can run the three numbers yourself.
Frequently asked questions
- Is cash back better than points?
- Cash back is simpler and its value is fixed. Points can be worth more per dollar spent, but only if you redeem them for more than one cent each, which usually means transferring them to airline or hotel partners. If you will not do that, cash back usually earns the same or more.
- What is a point worth?
- It depends on the program and the redemption. Many bank points are worth about one cent each toward travel or a statement credit, and some programs pay less than that for cash. Transfers to travel partners can be worth more. Our program pages show a value range for each program.
Cards in this article
Citi Double Cash Card
Citi · Mastercard Standard
- Fee
- $0
- Bonus
- $200 cash back
- Base
- 2X
5X Hotels · 5X Car Rentals · 5X Attractions
Wells Fargo Active Cash Card
Wells Fargo · Visa Signature
- Fee
- $0
- Bonus
- $100 cash back
- Base
- 2X
Chase Freedom Unlimited
Chase · Visa Signature
- Fee
- $0
- Bonus
- $200 cash back
- Base
- 1.5X
5X Travel · 5X Hotels · 5X Flights · 5X Car Rentals
Chase Sapphire Preferred Card
Chase · Visa Signature
- Fee
- $95
- Bonus
- 75,000 points
- Base
- 1X
5X Travel · 5X Hotels · 5X Flights · 5X Car Rentals
Keep reading
Points & Miles
Why the cash price you would pay matters more than a luxury sticker price
A $10,000 fare booked with points did not save you $10,000. Value an award three ways: sticker price, cash you would really pay, and what the upgrade is worth to you.
5 min read
Points & Miles
Amex Membership Rewards: how to build a practical redemption plan
Give Membership Rewards points a job. Compare Amex Travel, charge coverage, and airline transfers, including the U.S. airline transfer fee, before moving any.
5 min read
Points & Miles
Chase Ultimate Rewards: choose a redemption before choosing a transfer
Price a trip three ways before moving Chase points: cash back, Chase Travel, and a partner award. How transfer ratios and rounding change the real cost.
6 min read